The Global Supply Chain Crisis and What Comes Next
8 October 2026
In early 2020, a hospital administrator in Ohio tried to order N95 masks from a supplier she had used for years. The answer came back in hours: none available, no timeline for restocking. Within weeks, the same shortage hit grocery stores, car dealerships, and furniture retailers. A system that had quietly delivered goods on time for decades suddenly looked fragile. That moment marked the start of a supply chain crisis that reshaped how the world moves, makes, and buys things.
Most coverage of this crisis focuses on port congestion and shipping delays. That is like describing a heart attack as chest pain. The discomfort is real, but the underlying disease is structural. This article goes deeper: what actually broke, why the fixes are harder than they sound, and how business leaders should think about the next five years.
What Actually Broke
The global supply chain was not designed as a single system. It evolved. Over forty years, companies optimized for one variable above all others: cost. Factories moved to wherever labor was cheapest. Inventories shrank under just-in-time principles. Suppliers consolidated until a handful of firms controlled entire categories of components.This worked spectacularly, until it did not. The efficiency came with hidden fragility, and the pandemic exposed it in three ways.
First, demand shifted violently rather than declined. People stopped buying restaurant meals and started buying laptops, exercise equipment, and home office furniture. Factories built for one product mix could not instantly switch to another. A semiconductor plant that makes chips for cars cannot pivot to chips for game consoles without years of retooling.
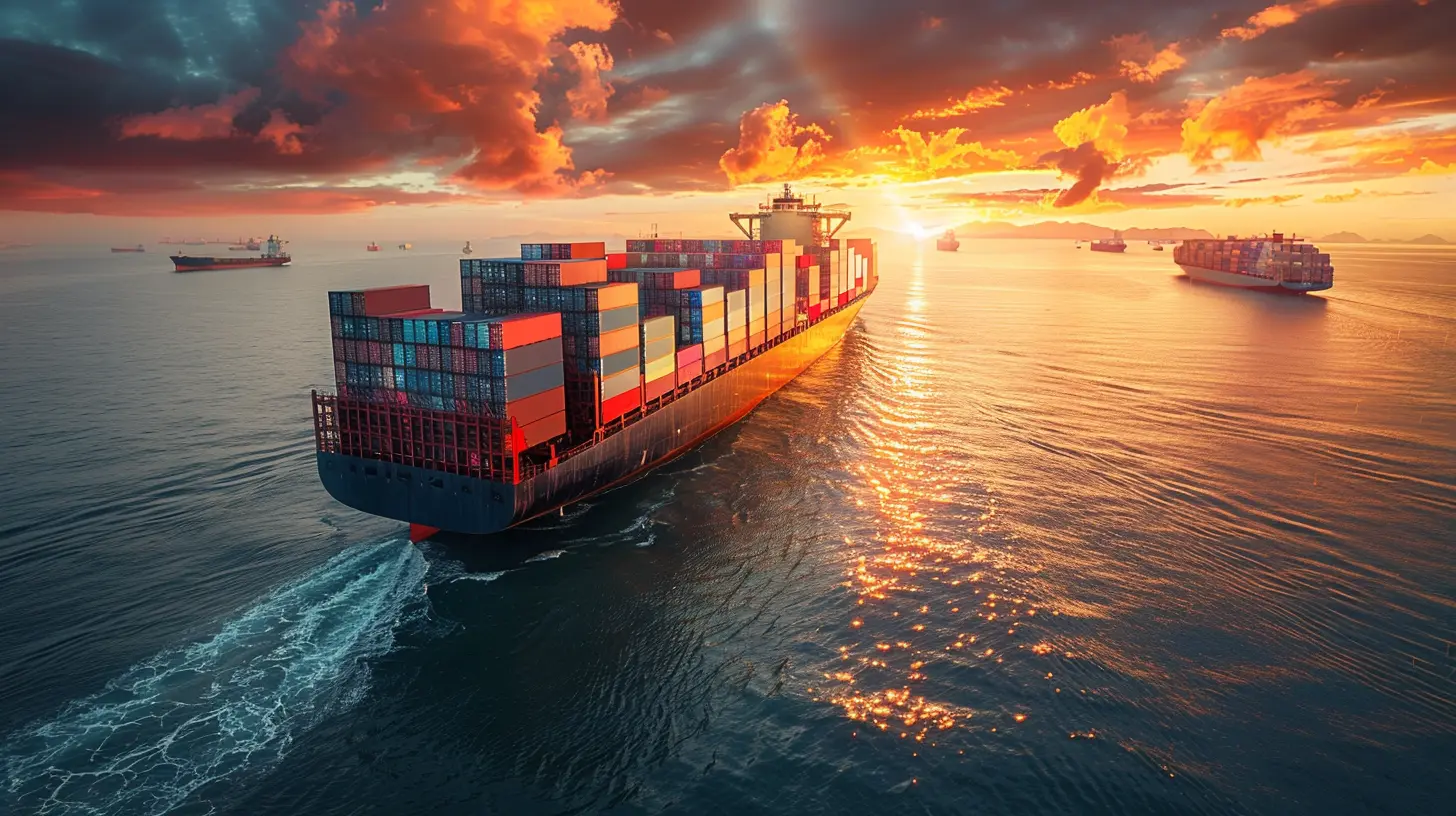
Second, logistics became the bottleneck. When demand surged, ports, trucks, and containers were already running near capacity. A single container ship blocking the Suez Canal in 2021 showed how one disruption could ripple across continents within days.
Third, labor shortages compounded everything. Truck drivers, warehouse workers, and port crews were already in short supply before 2020. The pandemic accelerated retirements and reduced immigration in many countries, tightening a market that had little slack to begin with.
The result was not a broken system. It was a system working exactly as designed, for conditions that no longer existed.
Why the Obvious Fixes Are Harder Than They Look
When shortages hit, the natural response is to build more factories, hold more inventory, and diversify suppliers. Each sounds simple. Each carries trade-offs that rarely make headlines.Reshoring and Nearshoring
Moving production closer to the end market reduces exposure to distant disruptions. A company that makes appliances in Mexico for US customers avoids transpacific shipping risk entirely. Governments have encouraged this with subsidies and tariffs.But reshoring rarely reduces total cost. Labor in developed markets is more expensive. Environmental and safety regulations add overhead. Skilled workers may not exist in the target region. A semiconductor fabrication plant takes three to five years to build and costs billions before it produces a single chip. For low-margin products like basic apparel or toys, reshoring often makes no economic sense at all.
The right question is not "should we reshore?" It is "which parts of our supply chain justify the premium?" Critical components, products with national security implications, and items where lead time matters more than unit cost are strong candidates. Commodity goods with stable demand are usually not.
Inventory Buffers
During the crisis, companies that held extra inventory outperformed those running lean. Retailers with stock on hand captured sales while competitors turned customers away. This pushed many firms to abandon just-in-time in favor of just-in-case.The trade-off is capital. Inventory ties up cash, requires warehouse space, and risks obsolescence. A fashion retailer holding six months of stock may write off half of it when trends change. A electronics manufacturer holding extra chips may find them outdated within a year.
The practical middle ground is segmentation. Hold buffer stock for items with long lead times, volatile demand, or few suppliers. Keep lean inventory for stable, easily sourced goods. Blanket policies in either direction waste money.
Supplier Diversification
Adding a second supplier sounds prudent until you try it. Many industries have consolidated so heavily that viable alternatives do not exist. Aerospace-grade titanium, advanced lithography equipment, and certain pharmaceutical ingredients come from a small number of sources worldwide. Qualifying a new supplier can take years and require extensive testing.Even when alternatives exist, they often share the same vulnerabilities. Two chip suppliers in the same region both face the same earthquake risk. Two factories in the same country both face the same export restrictions. True diversification means geographic and political separation, not just a second purchase order.
The Hidden Cost of Complexity
Every supply chain decision creates a web of dependencies that is hard to see until something breaks. A car manufacturer may know its direct suppliers. It rarely knows its suppliers' suppliers, or theirs. When a fire at a single plant in Japan halted production for automakers worldwide in 2021, most of them had never heard of the company.This opacity is the real crisis. Companies optimized for cost without mapping their exposure. They discovered their vulnerabilities only when they became failures.
Building visibility is unglamorous work. It means tracing materials back to raw sources, auditing subcontractors, and maintaining relationships with suppliers several tiers down. It requires data systems that most firms do not have. But without it, risk management is guesswork.
A useful starting point is to identify single points of failure: components, suppliers, or routes where no backup exists. Then ask what happens if each one goes down for a month. The answers usually reveal priorities faster than any risk matrix.
What Comes Next: Five Shifts to Watch
The crisis is not ending. It is evolving. Several structural changes are underway that will define the next decade.1. Regionalization Over Globalization
The era of one global supply chain optimized for cost is fading. In its place, regional networks are forming. North America, Europe, and Asia are each building more self-contained production ecosystems. This does not mean the end of global trade. It means trade patterns will shift toward regional partners and allies.For businesses, this changes location strategy. A company serving European customers may produce in Eastern Europe or North Africa rather than Southeast Asia. A US firm may favor Mexico over China. The calculus now includes resilience and political risk, not just labor rates.
2. Automation as a Response to Labor Scarcity
Warehouses, ports, and factories are investing heavily in automation. Robots do not get sick, retire, or demand higher wages. They also do not call in sick during a pandemic.The trade-off is capital intensity and inflexibility. A fully automated warehouse cannot easily handle new product types. A robotic assembly line takes time to reconfigure. Automation works best for high-volume, predictable operations. For low-volume or highly variable work, human labor remains more adaptable.
Companies should automate where volume justifies it and where labor is genuinely unavailable. Automating simply to cut headcount often backfires when demand shifts.
3. Digital Visibility as a Competitive Advantage
Firms that can see their supply chains in real time will respond to disruptions faster than those relying on quarterly reports. This means investing in tracking technology, supplier data platforms, and analytics that flag problems before they become crises.The challenge is that many suppliers, especially smaller ones, lack digital systems. Building visibility requires helping them modernize, not just demanding data. Companies that treat suppliers as partners in this effort will move faster than those that dictate terms.
4. Strategic Stockpiles and Government Intervention
Governments are treating certain supply chains as infrastructure. Semiconductor fabrication, pharmaceutical ingredients, and critical minerals now receive subsidies and protection in the US, Europe, and Asia. This is a significant shift from the free-market orthodoxy of recent decades.For businesses, this creates both opportunity and risk. Subsidies can lower the cost of building domestic capacity. They can also distort markets, create overcapacity, and lock companies into politically favored locations that may not be efficient long term. Leaders should evaluate government support carefully, not chase every incentive.
5. A New Definition of Efficiency
The old definition of efficiency was cost per unit. The new definition includes resilience, speed, and flexibility. A supply chain that costs 10 percent more but recovers from disruption in days instead of months may be far more valuable.This shift requires new metrics. Companies should track lead time variability, supplier concentration, and recovery time alongside traditional cost measures. Boards and investors are starting to ask for these numbers. Firms that cannot provide them will struggle to justify their strategies.
Practical Advice for Business Leaders
The crisis has produced a lot of noise. Here is what actually matters.Map Your Exposure Before You Act
Do not reshore, stockpile, or diversify until you know where your vulnerabilities are. Start with a tier-one supplier list, then push deeper. Identify single points of failure and estimate the cost of a disruption. This exercise often reveals that the biggest risks are not where executives assumed.Segment Your Strategy
Treat different parts of your supply chain differently. Critical components need buffers and backups. Commodity items can stay lean. High-margin products can justify premium suppliers. Low-margin products cannot. A one-size-fits-all approach wastes money on low-risk areas and leaves high-risk areas exposed.Build Relationships, Not Just Contracts
Suppliers prioritize customers who treat them well during good times. When shortages hit, those relationships determine who gets allocated product. Paying on time, sharing forecasts, and investing in supplier capabilities pays off when capacity is tight. Transactional relationships fail under stress.Invest in Visibility
You cannot manage what you cannot see. Invest in systems that track inventory, shipments, and supplier health in real time. Start with your most critical products and expand from there. Perfect visibility is impossible, but better visibility is always achievable.Plan for Scenarios, Not Predictions
No one predicted the pandemic. No one predicted the Suez blockage. The next disruption will also be unexpected. Instead of trying to predict the future, build plans for a range of scenarios: supplier failure, port closure, demand spike, demand collapse. Companies with rehearsed responses recover faster than those improvising.
Common Mistakes and Misconceptions
Several beliefs about supply chains are widely held and wrong.The first is that resilience means redundancy. Duplicating every supplier and stockpiling every component is prohibitively expensive and often impossible. Resilience means knowing which risks matter and addressing those, not eliminating all risk.
The second is that technology solves everything. Software can improve visibility, but it cannot create capacity, qualify suppliers, or move goods. Technology is a tool, not a strategy.
The third is that this is temporary. The crisis will end, but the conditions that caused it will not. Labor shortages, geopolitical tension, and climate disruption are long-term trends. Companies waiting for a return to 2019 will be waiting a long time.
The fourth is that only large companies can adapt. Small firms often have advantages: closer supplier relationships, faster decision-making, and flexibility. They may lack resources, but they can pivot quickly. Size is not destiny.
The Bottom Line
The global supply chain crisis exposed a truth that was always there: efficiency and resilience trade off against each other. For decades, businesses chose efficiency. Now they are paying for it.The path forward is not to abandon efficiency but to rebalance. Some redundancy is worth the cost. Some visibility is worth the investment. Some suppliers are worth the premium. The companies that find the right balance will outperform those that swing to either extreme.
This is not a problem to solve once. It is a capability to build. The firms that treat supply chain resilience as an ongoing discipline, not a project, will be the ones still standing when the next crisis hits.
all images in this post were generated using AI tools
Category:
Industry AnalysisAuthor:
Susanna Erickson